

Markets now have a reason to rethink the path of interest rates. Markets also had a reason to think about it yesterday. And last month. Thinking is free. Being right costs extra.
The theory goes like this. An Iran war resolution lowers the pressure on prices. Slower U.S. growth cools the economy. Fresh fiscal policy does something, probably. Rate hikes get curbed. Possibly. None of it is set in stone.
Read that last part again. The analysts gave you three maybes and a shrug, then called it a thesis.
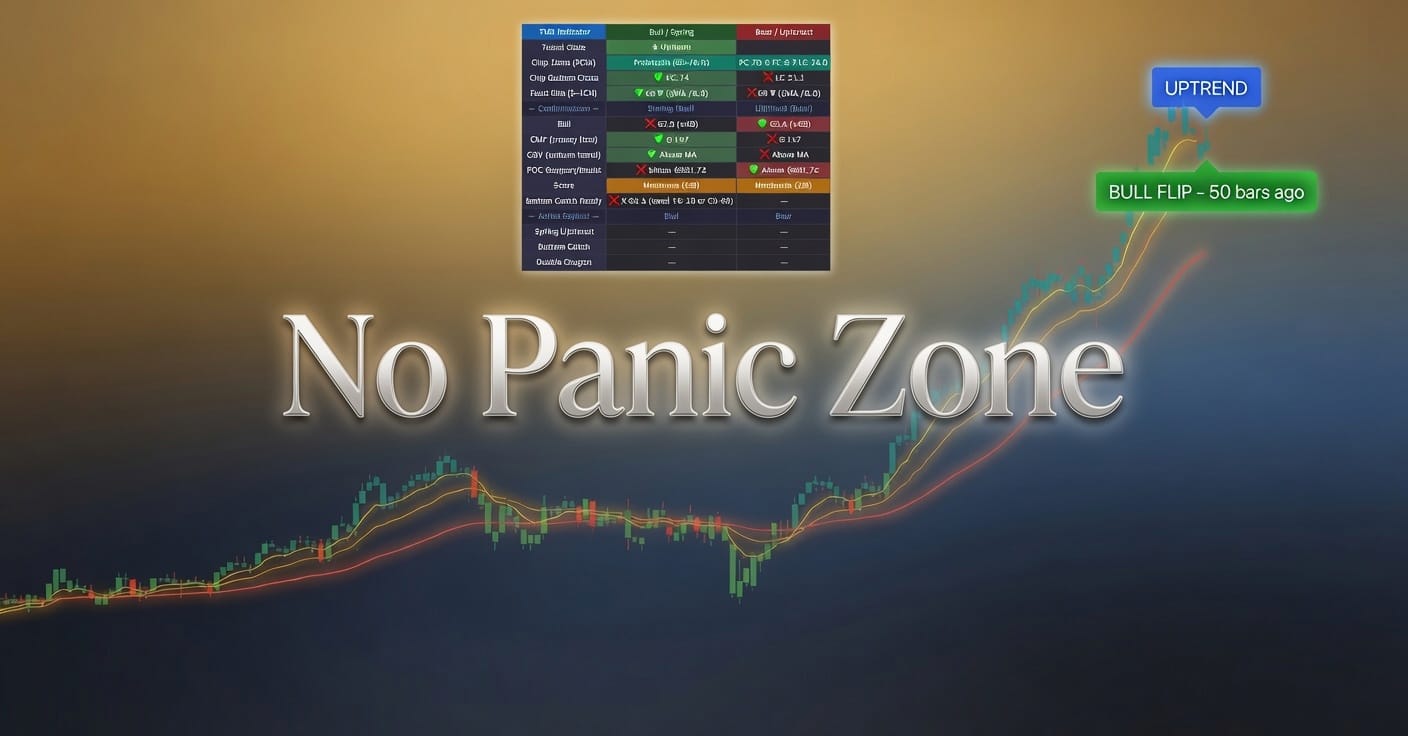
Here is a technical analyst's take on a sweep. A chart does not know who won. The 10-year yield does not read a ballot. It reads a trendline, and the trendline does not care about your feelings or your yard sign.
Retail traders will disagree. They will buy rate-sensitive stocks tomorrow morning because a headline said "rethink." They will call it a macro view. It is a mood with a brokerage login.
Consider the dependencies. Iran must resolve. Growth must slow, which is a strange thing to root for, but here we are. Congress must produce fiscal policy, an event rarer than a clean bathroom at a Waffle House. Three coin flips, all landing the same way. Your odds are roughly those of your cousin's options trade.
The Federal Reserve will do what it does. It will stare at data for six weeks, then act surprised by the data. Somewhere a strategist will say "data dependent" with a straight face and collect a bonus.
The summary says none of this is set in stone. Neither is your portfolio. Stone at least holds its value.
Buy the rethink. Sell the rethink of the rethink. Then explain to your spouse why the down payment is now a lesson.
Photo by Marcus Reubenstein on Unsplash


Leave a Comment